Educational Pack · 12
Non-Principal-Protected Structured Products
Source PDF: GUIDE-TO-UNDERSTANDING-ASSET-CLASSES-NON-PRINCIPAL-PROTECTED-STRUCTURED-PRODUCTS.pdf
U Wealth : Your partner in mastering financial instruments. We want you to feel comfortable making suitable investment decisions based on knowledge of the opportunities and risks of given financial instruments. — September 2026
What are structured products?
Structured products are synthetic investment products that usually combine two or more financial instruments, one of them often being an option.
The purpose is to tailor the risk properties, which cannot be found in standard financial instruments, in order to suit the specific market expectations and investment objectives of investors.
Structured products can give access to markets not easily covered by other financial instruments.
Structured products are available for a range of risk categories.
This document focuses on non-principal protected structured products such as yield enhancement or participation products. Additional explanatory material is available for principal protected products as well as for leveraged products.
In case of ETP, product could also consist of only one Digital Asset as underlying which is not classified as a financial instrument.
Advantages / disadvantages
Advantages
- Can be used to reduce risk by adding them to an existing portfolio. They provide capital protection and volatility reduction.
- They cater to market expectations not easily met by other instruments, e.g. sideways movements of markets or low-yield market environments.
- They can offer yield enhancement.
- They have the potential for enhanced returns.
- There is a broad range of assets available.
- They are tailored to investors' expectations.
Disadvantages
- Returns are not easily predictable.
- There can be price uncertainty.
- Because they are tailored, the market may be less liquid.
- Structured products are in most cases unsecured debt, and the credit quality of the issuer (issuer risk) needs to be considered.
- Structured products may be difficult to understand, depending on the product.
The advantages and disadvantages of structured products are highly product-specific.
Important risks to consider
Important risks
- The choice and quality of the issuer are important. – Structured products expose the issuer of the product, not the issuer of the underlying, to risks. – Structured products are very specific instruments; such liquidity may be less than with other products and depends on the issuer’s market making.
- Structured products often include option characteristics: the price of the product does not move in a linear way due to varying pricing factors. Thus, the pay-off profile may only be reached at maturity.
- If the product is quoted in a different currency, the additional currency risk needs to be considered. Specific structured products may hedge this risk (quanto).
Each structured product has its own risk characteristics and suitability for individual market expectations. It may enhance or limit the market risks to which the underlying asset is subject. The following product categories are important.
| Product category | Risk | Short description |
|---|---|---|
| Capital protection | Less risk | A product that guarantees a limitation of the risk of total loss under certain conditions. |
| Yield enhancement | A product that combines a fixed income product with an option. | |
| Participation | A product that usually carries the full risks of the underlying with/without contingent capital protection. | |
| Leverage | Products that make use of leverage effects to maximise possible returns at the risk of total loss. | |
| Leverage with knock-out | More risk | Products that make use of leverage effects to maximise possible returns at the risk of total loss. |
What to expect from structured products
| Investment horizon | Income expectation | Market expectation |
|---|---|---|
| Short term | Capital gain | Different product categories cater to different market expectations. See following pages for further details. |
| Medium term | Regular interest | |
| Long term | Irregular dividends |
Important to know before investing in yield optimisation
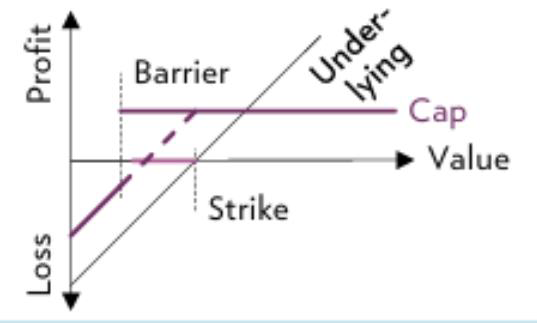
| Class | Discount certificate | Express certificate | Barrier reverse convertible |
|---|---|---|---|
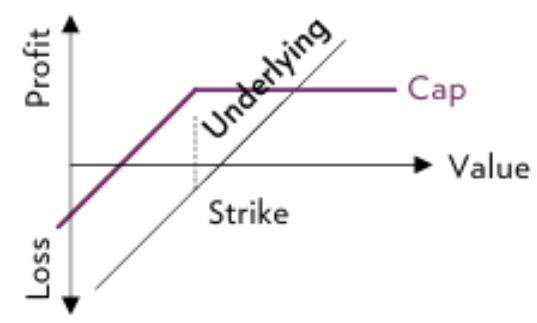
| Maximum gain | Discount given at issue | Coupon paid | Coupon paid |
| Maximum loss | Total loss of capital invested | Total loss of capital invested | Total loss of capital invested |
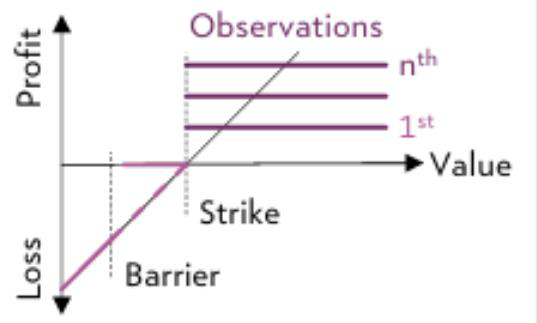
| Profit/loss | Issue price at a substantial discount to strike. Delivery of underlying if value is below strike at maturity. If the value is above strike at maturity, delivery of strike price in cash. | The following possibilities arise on every observation date: Early redemption of nominal plus coupon if underlying is above strike. Delivery of underlying if underlying is below barrier. Nominal preserved above barrier. | Coupon is paid independent of value of the underlying. If value above strike, then nominal and coupon are paid. If an underlying touches barrier, then physical delivery is possible. Nominal preserved above barrier. |
| Expectations | Decreasing volatility in sideways or slightly increasing tendencies | Sideways or slightly increasing tendencies. No decrease beneath barrier | Decreasing volatility in sideways or slightly increasing tendencies. No decrease beneath barrier |
| Specific risks | When below strike, the certificate reflects the market risks of the underlying asset. | If the value of the underlying assets falls below the barrier, the loss can theoretically be as high as the capital invested, with the exception of any coupon payment that took place. The price of the product may fall already if the underlying value drops near the barrier without touching it. |
Comments
- In some cases, capital protection may be combined with other certificates, e.g. express certificates.
- The underlying may be one or several assets, each with an individual barrier. Such products may deliver the worst performance only if any of the assets touches its barrier and closes below strike at maturity.
- Depending on the product type, barriers are either observed continuously or on certain days (American/European option component).
Important to know before investing in participation products
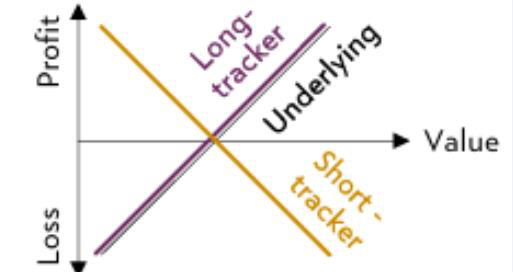
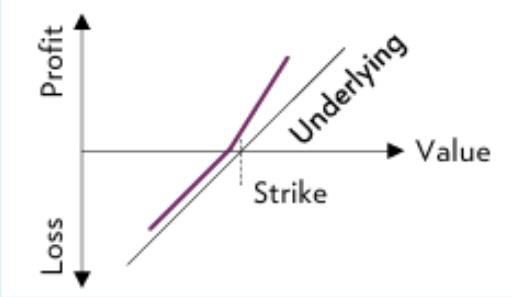
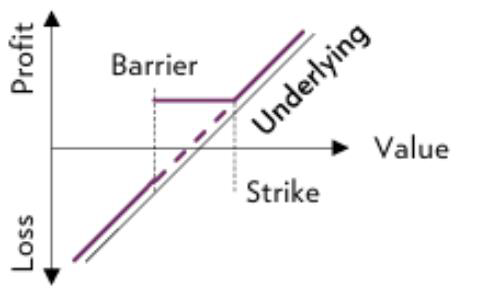
| Class | Tracker certificates | Outperformance certificates | Bonus certificates |
|---|---|---|---|
| Maximum gain | Reflect performance of underlying asset | Performance of underlying asset multiplied by participation | |
| Maximum loss | Total loss of capital invested | Total loss of capital invested | Total loss of capital invested |
| Profit/loss | Participation in the performance of an underlying. Can be short or long trackers. Usually uses a basket of underlying | Participation in the performance of the underlying. Example: a call-based certificate: 1:1 below strike. Over-proportional above strike | Participation in the performance of the underlying. Redemption of nominal when above barrier. Below barrier and above strike, the product is a tracker certificate |
| Expectations | For either rising or decreasing values of underlying(s) | Rising volatility value of underlying | Sideways or increasing tendencies of underlying, but no decrease towards barrier |
| Specific risks | Risks reflect the market risks of the underlying(s) | Certificates include options. The price of the certificate may therefore react in a non-linear way to price changes of the underlying asset. |
Comments
Certificates with several assets as underlyings bear risks that differ from those that a mutual fund is exposed to. The aim of the structured product is not necessarily diversification but to track and participate in the (very specific) assets selected. The investor participates intentionally in the specific risks of the underlyings. Additionally, unlike mutual funds, certificates are not secured debt.
A closer look at yield enhancement & participation products
Common features concerning risk exposure
The specific risks of structured products have to be evaluated in detail on a product-by-product basis. Nevertheless, structured products have some common features as far as their risk exposure is concerned.
- Investing in structured products is not the same as investing directly in the underlying assets involved. While a structured product inherits the risk exposure of its underlying (specifically its market risks), the combination adds new features (opportunities as well as risks).
- In many cases, structured products include an option component. This results in non-linear pricing behaviour.
- Structured products are tailored by an issuer. They constitute a debt obligation of the issuer and are not preferred debt. Hence, the investor is exposed to the credit risk of the issuer.
- The increased complexity may cause the liquidity risk to be higher than with other, more standardised investment products.
- Costs/fees are usually calculated in the structured product's issue price. The cost transparency for the investor is therefore not always as clear as with other investment products (e.g. funds).
- If the product itself, or one of its underlyings, is quoted in a different currency, the currency risk needs to be considered. Specific structured products may hedge the currency risk ('quanto').
- The time to maturity has to be evaluated carefully for structured products. – Maturity varies highly and depends on the product's features. – Certain products may reach their pay-off profile only at maturity or on specific dates. Although the product is liquid, its pricing behaviour before maturity may not be linear like at maturity (e.g. capital protection is only valid at maturity, not before).
- Legally, structured products constitute individual contracts with the issuer. A very wide range of structured products is available. It is beyond the scope of this educational material to describe all their aspects. It is therefore important to refer to the product disclosure documents (terms and conditions) for detailed characteristics and risk disclosure.
(1) Structured products are not funds and are therefore not subject to the regulations on collective investment schemes.
Yield optimisation products (1/2) — examples
Yield optimisation – barrier reverse convertible
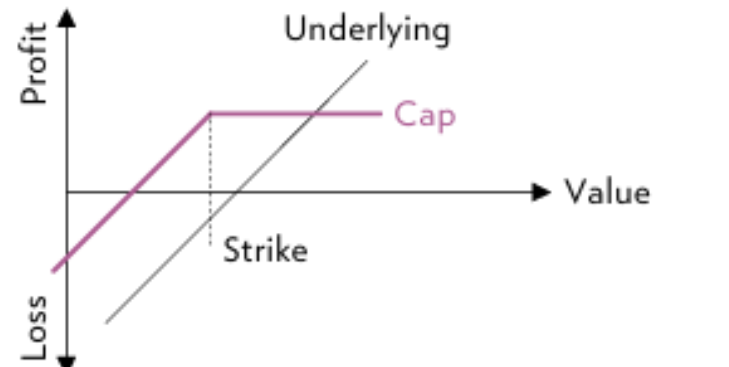
Properties at issue
- Nominal = CHF 1,000
- Maturity = one year
- Coupon = 11% per annum
- Underlying is a basket of three shares
| Share 1 | Share 2 | Share 3 | |
|---|---|---|---|
| Currency | CHF | CHF | CHF |
| Strike | 50.4 | 97.8 | 33.24 |
| Knock-in | 32.73 | 63.57 | 21.60 |
| Ratio | 19.84 | 10.23 | 30.08 |
Redemption scenarios at maturity
| Scenario | Details |
|---|---|
| Scenario 1 – No asset touched barrier at all | Lowest quotation: 44.59 – 68.90 – 25.20. Closing price: 56.35 – 69.40 – 35.50. Redemption of nominal: CHF 1,000. Coupon payment: CHF 110. Total redemption: CHF 1,110 |
| Scenario 2 – Barrier event occurred, but closing prices are all above strike | Lowest quotation: 44.59 – 56.55 – 25.20. Closing price: 62.66 – 103.74 – 35.95. Redemption of nominal: CHF 1,000. Coupon payment: CHF 110. Total redemption: CHF 1,110 |
| Scenario 3 – Barrier event occurred and at least one closing price is below strike | Lowest quotation: 44.59 – 56.55 – 25.20. Closing price: 56.35 – 69.40 – 33.00. Redemption of worst performer (Delivery of share 2): 10 × 69.40. Cash settlement for fraction with share 2 (0.23 shares × 69.40): CHF 16. Coupon payment: CHF 110. Total redemption: CHF 820 |
Remarks
- The coupon paid is independent of the performance of underlying asset
- Usually the worst performer is delivered. See Scenario 3: the barrier was touched but the performance of Share 2 is highly negative (-32.9%) compared with Share 2 in this example.
- Pay-off profile is only reached at maturity. Before maturity, the product may behave in a non-linear way.
Yield optimisation products (2/2) — examples
Yield optimisation – reverse convertible on foreign exchange
Properties at issue
| Property | Value |
|---|---|
| Underlying | Foreign currency / home currency |
| Spot price | 0.9532 (XYZ/CHF) |
| Strike price | 0.9532 (XYZ/CHF) |
| Coupon | 20% per annum |
| Maturity | 1 month |
| Minimum investment | CHF 250,000 |
Redemption scenarios at maturity
| Scenario | Details |
|---|---|
| Scenario 1 – Exchange rate > strike price (home currency is weaker) | Nominal amount and coupon paid back in home currency (e.g. conversion rate at maturity is 0.981). Redemption = CHF 250,000 + CHF 4,167 = CHF 254,167 |
| Scenario 2 – Exchange rate < strike price (home currency is stronger) | Nominal amount and coupon are paid in conversion currency converted at strike! Redemption = (CHF 250,000 + CHF 4,167) / 0.9532 = XYZ 266,646. The current value at maturity of this redemption amount in CHF (e.g. conversion rate at maturity is 0.92): Redemption = XYZ 266,646 × 0.92 = CHF 245,314.32 |
Remarks
- Reverse convertibles on foreign exchange are usually over-the-counter traded instruments
- Reverse convertibles with underlying shares are traded on secondary markets working price, home.
- The coupon payment is independent of the performance of underlying.
- The investor is exposed to market risks of the underlying asset case above currency risk may be high; therefore scenario analysis is important.
- Reverse convertibles on foreign exchange cannot be sold prior to maturity so are not secondary market instruments.
- Liquidity is therefore very limited.
Participation products — examples
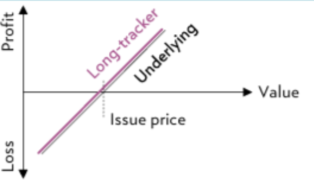
Participation – tracker certificate (long)
Properties at issue
- Issue price CHF 99 (99%)
- Initial value CHF 100
- Participation 100 %
- Maturity 1 year
- Underlying is a basket of four shares
| Ref. price [CHF] | Weight in basket | No. of shares | |
|---|---|---|---|
| Share 1 | 22,365 | 0.25 | 1.12 |
| Share 2 | 384,585 | 0.15 | 0.039 |
| Share 3 | 33,353 | 0.30 | 0.90 |
| Share 4 | 76,465 | 0.30 | 0.39 |
Calculation method — Total value of basket is calculated as: Σ (closing price × no. of shares per basket)
Redemption scenarios at maturity — Scenario 1
| Closing prices | No. of shares | Redemption value | |
|---|---|---|---|
| Share 1 | 23.25 | 1.12 | 25.99 |
| Share 2 | 375.23 | 0.039 | 14.64 |
| Share 3 | 34.22 | 0.90 | 30.78 |
| Share 4 | 79.35 | 0.39 | 31.17 |
| Total redemption value | 102.54 |
Remarks
- The investor directly participates in the performance of underlying asset.
- Participation may be more or less than 100%, depending on specific product.
- Risk is linked to market risk by the investor to the market risks of the underlying asset as a whole.
- Currency risk emerges in those cases where product currency not home currency of investor, when individual underlying quoted in currency different from the product's currency. Some products hedge the currency risk ('quanto').
A closer look at exchange traded products (ETP)
What are ETP?
- ETP are a sub-category of structured products and hence are technically considered as structured products but can also have many elements of fund similar instruments
- The main difference is that ETP are listed and traded on exchanges while structured products are mostly traded on primary markets
- ETP can be benchmarked to various investments categories, such as commodities, currencies, stocks, bonds or digital assets
| Structured product (SP) | Exchange traded product (ETP) | |
|---|---|---|
| Legal structure | Often unsecured debt obligations of financial institutions | Legally ETPs are non-interest bearing notes (structured products). Usually set up via Special Purpose Vehicle (SPV) |
| Ownership of underlying asset? | Debt contract promises return linked to underlying asset; but SP may be hedged (1:1) or not | Debt contract promises return linked to underlying asset. ETP are typically 100% collateralized. Can trade at premium/discount to NAV and has counterparty risk |
| Trading | Mostly primary markets (subscription and redemption at NAV). Secondary trading possible: Issuer makes OTC market | Market making via Authorized Participants. Analogous to ETF: Trading difference minimized |
Important legal information
Legal entity
U Wealth SA – 8C avenue de Champel, 1206 Genève, Suisse. Supervised by FINMA (Swiss Financial Market Supervisory Authority).
Educational and Informational Disclaimer
Educational and Informational Disclaimer: This content is provided for informational and educational purposes only. It does not constitute marketing material, nor is it the result of independent financial/investment research. It has not been prepared in accordance with the legal requirements designed to promote the independence of financial research and is not subject to any prohibition on dealing ahead of the dissemination of such research. The content has been prepared by U Wealth SA, which is authorised and regulated by FINMA (Swiss Financial Market Supervisory Authority). The information may be updated irregularly or in response to significant developments.
Informational Purposes Only
Informational Purposes Only: All information and opinions were valid at the time of writing and are subject to change without notice. This document is provided for informational purposes only and does not constitute legal, tax, accounting or investment advice, nor does it constitute an offer or invitation to buy or sell any financial instrument. Opinions expressed herein reflect the current views of the authors but not necessarily those of U Wealth SA as a whole. While the information is believed to be accurate and sourced from reliable providers, U Wealth SA makes no warranty as to its accuracy, completeness, or timeliness. U Wealth SA accepts no liability, to the extent permitted by law, for any direct or indirect damages or losses arising from the use of this material or any decisions taken based on it.
Suitability & Professional Advice
Suitability & Professional Advice: Investments mentioned may not be suitable for all investors. Each investor should consider the suitability of an investment to their personal circumstances and objectives and consult their professional advisor before making any financial decision. This content does not constitute a personal recommendation and does not take into account your personal investment profile or financial situation.
Sustainability / ESG
Sustainability / ESG: This material does not necessarily adhere to ESG regulations or standards that may apply in other jurisdictions. For details on ESG criteria and any potential impact on financial return or investment eligibility, please contact U Wealth directly.
General Risks
General Risks: The value of and income from investments may rise or fall, and investors may not recover the amount invested. Financial instruments may be exposed to various risks, including but not limited to market, credit, political, and currency risks. Past performance and simulated returns are not reliable indicators of future performance. Structured products mentioned do not represent collective investment schemes under Swiss law and are not supervised by FINMA as such. Investors do not benefit from the specific protections provided by the Swiss Federal Act on Collective Investment Schemes.
Third-Party Data
Third-Party Data: Some information may originate from third-party providers such as credit rating agencies, financial data sources, or ESG data platforms. U Wealth SA does not guarantee the accuracy or completeness of this data and declines any liability related to its use.
Restricted Distribution
Restricted Distribution: This content is intended solely for recipients located in Switzerland and is not directed to any person or entity in any jurisdiction where its distribution would be contrary to local laws or regulations. This document may not be reproduced or distributed without prior written consent from U Wealth SA.
United States
UNITED STATES: NEITHER THIS CONTENT NOR ANY COPY THEREOF MAY BE SENT, TAKEN INTO OR DISTRIBUTED IN THE UNITED STATES OR TO ANY US PERSON. © U Wealth, 2025
Contact information
contact@uwealth.ch | +41 (0)22 545 51 40